

Lenme: Borrowing and Lending
by Lenme: Borrow and Lend
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
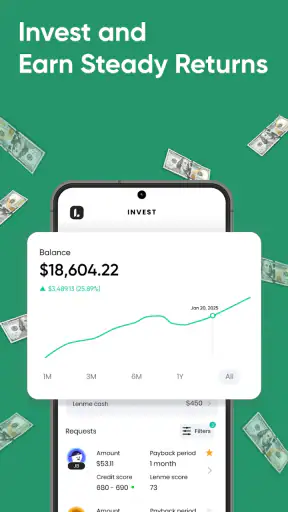
 Analysis by Getfullapps
When money is tight, the hardest part is often not finding a financial app but deciding whether it deserves access to your attention, personal details, and repayment planning. Lenme: Borrowing and Lending approaches that problem as a finance app for people looking for quick cash advances, personal loans, or lending opportunities. I found it most interesting as a marketplace-style tool rather than a simple budgeting app: it tries to connect people who need money with people interested in lending.
That distinction matters. This is not the same experience as opening a traditional bank app, checking a balance, or moving money between accounts you already control. The central question is whether the borrowing or lending opportunity fits your circumstances, and whether you are comfortable making decisions inside an app where financial information is involved. My overall impression is cautiously positive, but I would use it with a deliberate process rather than treating it as an instant solution whenever an unexpected bill appears.
How Lenme fits into real borrowing decisions
Lenme is developed by Lenme: Borrow and Lend and sits in the finance category. It is free to install, has an Everyone content rating, and has been available since January 10, 2019. Its current version is 26.6.1 and it requires Android 8.0 or later. The service has passed the point of being a little-known experiment: it has more than 500 thousand installs, with an average rating of 4.2 from around 22 thousand ratings.
Those figures give me useful context, but they do not remove the need for care. A large user base can indicate that an app is practical for many people, while a rating still represents a mixture of experiences. In finance, the details of a particular offer, repayment expectation, eligibility decision, and user situation matter more than popularity alone.
The app’s two-sided design is its defining feature. A borrower may use it when a short-term gap needs attention, while a lender may browse opportunities with the hope of earning a return. That creates a different set of responsibilities for each side. Borrowers need to understand the total obligation before accepting anything. Lenders need to think about risk, timing, and the possibility that money will not behave like cash held in a savings account.
A practical borrowing scenario
Imagine that a household has an urgent car repair before payday. The person may open Lenme to explore whether a personal loan or cash advance could help bridge the gap. The sensible workflow is not simply to request the largest amount available. I would first calculate the repair cost, the next reliable income date, and the amount that can be repaid without creating a second emergency.
That last step is where many quick-loan tools become uncomfortable. A loan can solve today’s problem while making the next few weeks harder. Lenme can be useful for comparing an available route with alternatives, but it should not encourage a person to borrow merely because an option appears on the screen. I would treat every displayed opportunity as something to investigate, not as a recommendation that automatically suits me.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For a lender, the scenario is different. Someone with spare funds might look for lending opportunities rather than leaving that money idle. The attraction is understandable, but I would not use money needed for rent, bills, or emergency savings. The trade-off is straightforward: a possible return comes with exposure to repayment uncertainty, and the app should not be confused with a guaranteed deposit product.
Trust begins with visible choices
My trust in a finance app comes less from polished wording and more from what I can see while using it. Before submitting a request, I want the amount, repayment terms, charges, and timing to be understandable. Before lending, I want enough information to judge whether the opportunity belongs within my risk tolerance. If an important condition is difficult to locate, I slow down rather than assuming the best.
This is also why I would keep Lenme separate from casual app browsing. I would install it from the official app marketplace, review the requested access during setup, and avoid granting anything that does not make sense for the task. I would also use a unique password and protect the phone itself. These are ordinary precautions, but they matter more when an app is connected to borrowing, lending, identity, or payment-related decisions.
The app is free to download, but in-app purchases are listed from $1.99 to $399.99 per item. That makes it especially important to distinguish installation cost from any later charge or paid action. I would inspect each confirmation screen carefully and avoid tapping through a payment step just to see what happens. A free download should never be interpreted as a promise that every service inside the app is free.
Controls I would check before committing
My first check would be the account profile. I would make sure my name and contact details are accurate, because a mistake in a financial profile can create friction later. Next, I would look for ways to review active requests, lending activity, repayment information, and account notifications. A finance app is easier to trust when I can tell what is pending, what has completed, and what still requires action.
I would also pay attention to confirmation language. A button that says “continue” is not as useful as a screen that clearly explains whether I am submitting an application, accepting an obligation, placing funds, or merely reviewing an opportunity. If the app presents a choice between borrowing and lending, I would confirm that I am in the correct mode before proceeding. This sounds basic, yet it is a valuable safeguard in an app with two very different user roles.
Account control also includes knowing how to pause my activity. If I no longer want to browse opportunities, I would look for a way to stop notifications or close the account rather than leaving an unused financial profile active. I would not assume that deleting the app removes the account or ends an obligation. Those are separate actions in many services, so I would resolve any outstanding activity first and then use the account settings or support route provided inside the product.
Another useful habit is keeping personal records. I would save confirmation screens, note repayment dates in my calendar, and compare the final terms with what I expected before accepting. This is particularly helpful when an offer changes between an initial request and a final approval. Screenshots and written notes are not a replacement for reading the agreement, but they make it easier to spot a mismatch and ask a precise question.
Handling sensitive information without rushing
Financial apps naturally bring sensitive moments: creating an account, requesting money, checking an offer, entering payment details, or deciding whether to lend. I would avoid doing those tasks on an unsecured public network and would keep the phone’s operating system updated. I would also review the app’s permissions in the device settings after installation, not just during the first launch. Android makes it possible to revisit permissions, and that gives me a practical way to keep control over access.
I would read the privacy and account terms before submitting information, especially if the app asks for details that feel unrelated to the particular action I am taking. The important point is not to assume that a finance app is automatically unsafe or automatically safe. It is to make an informed choice about what I am sharing, why it is needed, and whether I am comfortable continuing.
Notifications deserve attention too. A lock-screen alert about a loan request or financial activity could expose more than I want someone nearby to see. I would adjust notification previews if the phone is shared or regularly visible to other people. That is a small setting with a meaningful privacy benefit, particularly for users who do not want financial messages displayed in public.
I would also be cautious with messages claiming to represent the service. If an email or text asks me to reveal a password, send money outside the normal workflow, or install another application, I would stop and open Lenme directly instead of following the message. The safest route is to verify activity from inside the account and use the app’s own support process when something looks unusual.
What the app does well for careful users
The strongest part of Lenme is the way it brings borrowing and lending into one focused environment. Someone who wants to explore alternatives to a bank or a familiar credit provider can at least investigate another route. Someone interested in lending can see opportunities in a context designed around that purpose instead of trying to arrange everything through informal messages and spreadsheets.
I also appreciate that the app can encourage a more explicit decision than borrowing from a friend. Informal loans often leave repayment dates vague and create awkward conversations. A dedicated finance workflow can make the obligation feel more concrete. That benefit depends on reading the terms and keeping track of the commitment, but the structure itself can be helpful for people who want a clearer record.
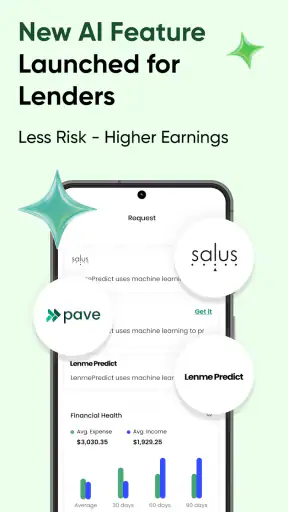
For lenders, the app may be more convenient than searching for individual borrowers independently. The convenience, however, should not be mistaken for due diligence. I would still evaluate how much money I can afford to have unavailable, how comfortable I am with delayed repayment, and whether the opportunity is suitable for my personal financial plan. The app can organize the process; it cannot make the underlying risk disappear.
The track record visible through its store presence also makes it easier to consider than an unknown finance download. Its average rating is 4.2, and the app has roughly 4.7 thousand written reviews. I see that as a reason to investigate it, not as a substitute for reading current terms and checking how the present version behaves on my device.
Where I would slow down
The biggest limitation is that speed can create pressure. Words such as quick cash and easy loans may appeal when a bill is urgent, but urgency is exactly when I am most likely to overlook a fee, repayment date, or eligibility condition. I would never accept an offer while distracted, upset, or trying to solve a crisis in a few seconds.
The two-sided model can also be confusing for a first-time user. Borrowing and lending are not minor variations of the same action. They involve opposite financial goals and different risks. I would take extra care to identify which role I am using, especially if I switch between exploring a loan and considering lending opportunities.
Another limitation is suitability. Lenme is not my first choice for routine money management, expense tracking, long-term saving, or building a complete household budget. A banking app is usually better for viewing existing accounts, while a budgeting app may be better for understanding spending patterns. A credit union or established lender may be preferable when I want a longer relationship, clearer branch support, or a product designed for a larger planned expense.
I would also skip it when I cannot explain how repayment will work. If my income is uncertain, the expense is ongoing, or the proposed commitment would require another loan to repay the first one, the app is not solving the underlying problem. In that situation, I would look for a nonprofit financial counselor, speak with the bill provider about a payment arrangement, or delay the purchase if possible.
Small habits that make the experience safer
- Calculate the repayment before requesting money. I would write down the amount I can comfortably repay and compare it with the complete obligation, not just the amount that arrives.
- Separate browsing from accepting. I would explore opportunities first, then leave the app and review the decision with a clear head before confirming anything.
- Keep lending money disposable. I would use only funds that are not needed for essentials, because a potential return is not the same as immediate access to cash.
- Review permissions and notifications. I would check device settings after setup and hide sensitive previews on the lock screen.
- Record every commitment. I would save the final details, add dates to my calendar, and check the account regularly instead of relying on memory.
These habits are more important than finding a clever way to use the interface. They turn the app from an impulse-driven shortcut into a tool for a measured financial decision. That is the difference between browsing because I am curious and using it because I have a plan.
Who should try it, and who should choose another route
I would recommend trying Lenme to a financially organized adult who wants to investigate short-term borrowing or lending opportunities and is willing to read every condition. It may suit someone who values a digital process and wants an alternative to approaching a traditional bank for a smaller, more immediate need. It can also interest a lender who understands that returns involve risk and who can leave the money committed without harming everyday finances.
I would not recommend it as a first stop for someone who is already juggling several debts, has no dependable repayment plan, or feels pressured to accept the first available option. I would also steer a person toward a conventional bank, credit union, or established personal-loan provider when the amount is substantial or the repayment period needs careful, face-to-face explanation. For everyday budgeting, a dedicated money-management app is likely a better fit.
Families sharing one financial plan may find a personal finance or banking tool more useful because Lenme is centered on borrowing and lending activity rather than a complete household overview. Likewise, someone seeking emergency assistance should consider local support services before adding a new obligation. The right alternative depends on the problem: cash flow, debt management, budgeting, or a planned purchase are not interchangeable needs.
My cautious verdict
After looking at Lenme as a finance tool rather than a magic source of money, I see a useful but responsibility-heavy app. Its free entry, established presence, and focused borrowing-and-lending model make it worth exploring for the right user. The value is greatest when I use it to compare a carefully calculated option, not when I open it hoping that speed will solve an unclear financial situation.
My recommendation is to use Lenme as a research and decision tool, never as an automatic green light to borrow or lend. Check the account controls, review permissions, understand every financial confirmation, and keep records of what you accept. The app can make an alternative route easier to investigate, but the quality of the outcome still depends on my judgment and ability to repay or absorb risk.
In short, I would keep it available for a specific, manageable use case and approach every offer slowly. If I needed a full budgeting system, long-term banking relationship, or professional debt guidance, I would choose something else. If I wanted to examine borrowing or lending opportunities with clear personal limits, Lenme: Borrowing and Lending could be a practical place to start, provided I remain in control of the decision.
Pros
- Clear loan requests help borrowers compare available funding options.
- Lenders can diversify funds across multiple borrowing requests.
- The app provides a convenient mobile-first lending experience.
- Repayment schedules make expected installments easier to track.
- Useful for users seeking alternatives to traditional bank loans.
Cons
- Loan availability may depend heavily on your profile and location.
- Returns for lenders are not guaranteed if borrowers miss payments.
- Fees and interest terms require careful review before accepting an offer.
- Identity and financial verification may take time to complete.
- The platform may not suit users needing immediate, guaranteed funding.
FAQs for Lenme: Borrowing and Lending
What is Lenme: Borrowing and Lending, and how does it work?
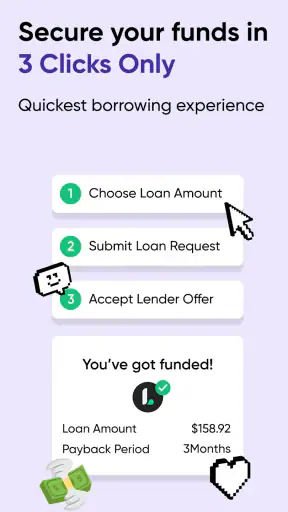
Lenme is a peer-to-peer lending platform that connects people seeking personal loans with individual investors willing to fund them. After creating an account, borrowers can submit a request with the desired amount, repayment period, and other details. Investors can review available requests and choose which ones they want to fund. Approval, funding, and repayment terms depend on the information provided and the platform’s current requirements.
Can anyone borrow money through the Lenme app?
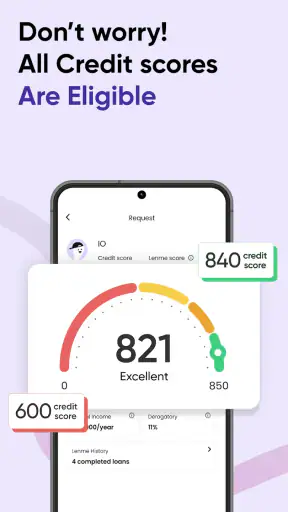
Not necessarily. Lenme typically requires users to meet eligibility conditions before they can request or receive funding. These conditions may include being of legal age, living in a supported location, providing identity and financial information, and linking an eligible bank account. Approval is not guaranteed, and the availability of a loan may depend on your profile, requested terms, investor interest, and applicable lending regulations.
How much does borrowing through Lenme cost?
The total cost can include interest, platform or service fees, and other charges associated with processing or repaying a loan. The exact amount depends on the loan terms, your borrower profile, and the offer available through the app. Before accepting anything, carefully review the annual percentage rate or equivalent cost, repayment schedule, late-payment consequences, and all applicable fees rather than focusing only on the amount received.
Is Lenme safe to use for borrowers and lenders?
Lenme may provide account security features and identity or financial verification processes, but no financial platform can eliminate every risk. Borrowers should protect their login details, read the lending agreement, and avoid sharing sensitive information outside the official app. Lenders should understand that peer-to-peer loans can carry a risk of delayed payments or default, and returns are not necessarily guaranteed.
What should I check before downloading and using Lenme?
Before installing Lenme, check whether the service is available in your country or state and confirm that your bank account and personal circumstances meet its requirements. Read the current privacy policy, terms of service, fee schedule, and repayment conditions. Also verify the developer name, app permissions, recent user reviews, and official support channels. Because loan products and regulations can change, rely on the latest in-app information.

Lenme: Borrowing and Lending
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@lenme.com, visit https://www.lenme.com, or review their https://www.lenme.com/privacy-policy.










